
Rental trust accounting is the legal process of holding and recording tenant and owner funds separately from an agency’s own money, with the Licensee in Charge personally responsible for its accuracy. In NSW, licensees must lodge an independent audit for the year ending 30 June within three months, and no later than 30 September. The immediate priorities are daily reconciliations, a registered Unique Identifying Number, and an auditor booked early.
Key Takeaways
Effective trust accounting relies on daily routines, proper reconciliation, timely audits, and partnering with specialists to ensure compliance and resolve disputes.
How healthy is your trust account?
Book a complimentary 30-minute Trust Account Health Check and see where your processes could be improved.
Book a Free Health Check →| Point | Details |
|---|---|
| Separate trust accounts | Trust funds must be kept in designated bank accounts with a Trust Account label, distinct from operational accounts. |
| Maintain detailed records | Monthly reconciliations of bank statements, ledgers, and client balances are essential for audit readiness. |
| Early audit planning | Book auditors early and complete required lodgements by deadlines to avoid fines and disciplinary actions. |
| Consistent daily discipline | Promptly receipt and deposit trust money, reference UID, and keep all supporting records organized. |
| Partner with specialists | Outsourcing trust accounting to providers like Reliance Property Accounts reduces compliance risk and eases daily workload. |
Table of Contents
- What trust accounting covers and how the rental ledger works
- Audit and lodgement requirements across Australia, NSW as the working example
- Daily and monthly routines that keep accounts audit-ready
- Common pitfalls and how to catch them before an auditor does
- Handling tenant bond monies within trust accounts
- How trust accounting disputes get resolved
- Outsourcing trust accounting: what a specialist partner actually does
- Get trust accounts handled by Reliance Property Accounts
- FAQ
- Sources
What trust accounting covers and how the rental ledger works
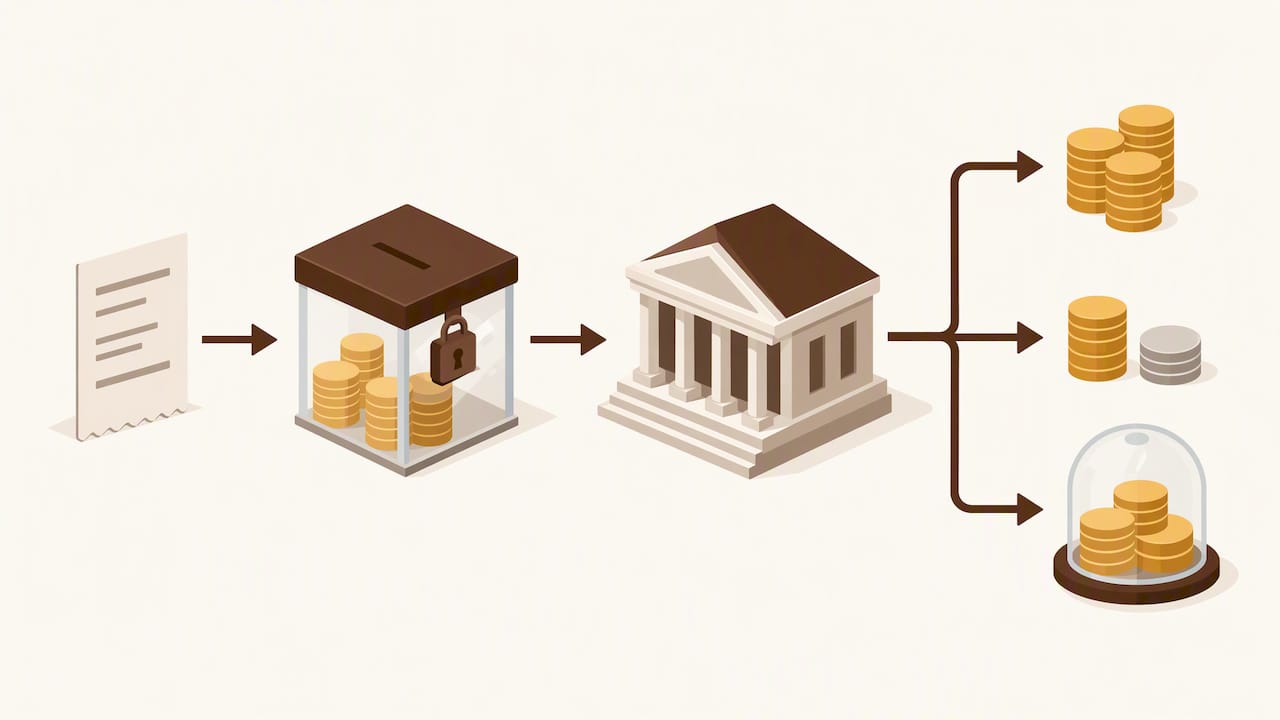
A trust account holds money that belongs to someone other than the agency: rent collected on behalf of landlords, tenant bonds before they’re lodged, and any other client funds passing through a property manager’s hands. This money is never mixed with the agency’s operating account, and it sits in a bank account that carries the words “Trust Account” in its name, a requirement tied to the Unique Identifying Number a Licensee in Charge must obtain before the account can be registered.
The rental ledger is the record that sits underneath all of this. It tracks every rent payment against a tenancy: the date paid, the amount, and a running balance showing whether the tenant is ahead, behind, or square. Landlords use the same ledger data to understand what’s been collected and disbursed on their behalf.
Tenants aren’t locked out of this information. In NSW, a tenant can request a written rent statement and the agent must provide it within seven days. Other states impose similar obligations, though the exact turnaround varies by jurisdiction.
Some distinctions worth holding onto:
- A trust account is separate from an agency’s general operating account, both legally and in the bank’s own records.
- The rental ledger records dates, amounts and running balances for each tenancy, not just a total.
- A rent statement request from a tenant triggers a statutory response window, seven days in NSW.
- Bank naming conventions (the “Trust Account” designation) are tied directly to the UID issued by the regulator.
Audit and lodgement requirements across Australia, NSW as the working example
Every trust account has an audit period, and in NSW that period ends on 30 June each year. The audit itself has to be completed and lodged within three months of that date, which means the hard deadline is 30 September. REINSW reminds members of this deadline every year, for good reason: it’s one of the most commonly missed compliance dates in property management.
Only auditors qualified under section 115 of the relevant legislation can sign off on these reports, and lodgement happens through the Auditor’s Report Online system rather than by post or email. A few things to keep in mind as the deadline approaches:
- The Licensee in Charge, not the bookkeeper or the auditor, carries the legal duty to ensure the audit is lodged on time.
- A trust account with zero transactions during the audit year still needs supporting documentation, including bank statements and the UID. There’s no automatic exemption for quiet accounts.
- Trust money held for two years with no successful contact with the owner must be forwarded to Revenue NSW, a step many agencies forget until an auditor flags it.
- Late or missing lodgement can bring fines, disciplinary action, or disqualification from holding a licence at all.
REINSW’s reminders to members have been followed by a 75% increase in the return of outstanding audits after disciplinary processes begin, a sign of how many agencies leave this until it’s already a problem.
Could outsourcing save your agency time and money?
Book a complimentary 30-minute Trust Account Health Check and see where your processes could be improved.
Book a Free Health Check →Booking an auditor early in the financial year, rather than in August when every other agency is doing the same thing, remains one of the simplest ways to avoid this scramble.
Daily and monthly routines that keep accounts audit-ready
Audit readiness isn’t something to build in August. It’s the output of habits repeated every working day. Rent and other trust money should be receipted and banked promptly, with the UID attached to the account so every deposit is traceable back to a registered trust account rather than a general one.
Monthly, the account needs a three-way reconciliation: the bank statement balance, the trust ledger total, and the sum of individual client balances all need to match exactly. Whoever prepares the reconciliation signs it, and the Licensee in Charge signs it too, creating a clear record of who checked what and when.
A practical monthly and daily routine looks like this:
- Receipt trust money the same day it’s received and deposit it promptly, referencing the UID on every transaction.
- Reconcile the bank balance, ledger total and client balances every month, with both preparer and LIC signing off.
- Export rental ledgers and owner statements on a regular cycle, whether through a tenant portal or in response to a written request.
- Keep bank statements, ledger exports, UID documentation and unclaimed money records organised and ready to hand an auditor without a scramble.
Pro Tip: Store every month’s signed reconciliation and supporting exports in a single, dated folder, digital or physical, so an auditor’s request never turns into a week of searching.
Owner statements and rental ledgers increasingly move through digital portals rather than printed reports, but the underlying obligation is the same: landlords and tenants are entitled to accurate, timely records of what’s moved through the trust account on their behalf.
Common pitfalls and how to catch them before an auditor does
Most trust account failures trace back to a handful of repeated mistakes, and auditors are trained to spot every one of them. Back-dating a reconciliation sign-off, or forging a Licensee in Charge’s signature on one, is treated as a serious compliance failure because it suggests the control wasn’t actually performed when it should have been. Mixing client funds between different owners’ ledgers, delaying disbursements past what’s reasonable, or leaving gaps in the paper trail all raise the same red flag: the daily discipline broke down somewhere.
A practical path back to clean records looks like this:
- Build a clean-up workbook that reconstructs every transaction against bank statements, month by month, until the ledger and the bank agree.
- Engage a qualified auditor as soon as a discrepancy is found, rather than waiting for the annual lodgement window.
- Notify Revenue NSW promptly for any unclaimed trust money that’s passed the two-year threshold.
- Escalate to internal legal counsel or the regulator directly when a discrepancy looks deliberate rather than accidental.
Catching a problem internally and fixing it before the annual audit is always a better position than an auditor finding it first.
Handling tenant bond monies within trust accounts
Tenant bonds carry an extra layer of care because they aren’t the agency’s money, the landlord’s money, or even fully the tenant’s money until the tenancy ends. Most Australian jurisdictions require bonds to be lodged with a government bond authority within a set number of days of receipt, rather than held indefinitely inside an agency’s trust account.
Until lodgement happens, the bond sits in the trust account like any other client fund: receipted promptly, recorded against the correct tenancy, and included in the monthly three-way reconciliation. Agencies that hold bonds longer than the required lodgement window, or that let bond funds blur into general rent receipts on the ledger, create exactly the kind of discrepancy an auditor is trained to find.
At the end of a tenancy, the bond’s disposition, whether refunded in full, partly claimed, or disputed, needs to be documented clearly, with both parties’ agreement or a tribunal order on file. Treating bond handling as a distinct process from routine rent receipting, rather than folding it into the same workflow, is one of the more reliable ways to avoid errors here.
How trust accounting disputes get resolved
Disagreements over trust account records usually start small: a tenant disputes a rent statement balance, or a landlord questions a disbursement amount. The first step is almost always internal, pulling the rental ledger and bank records for the period in question and checking them against what was communicated.
When the records are clear and accurate, most disputes resolve at this stage with a corrected statement or a straightforward explanation. When they don’t, tenancy disputes typically escalate to the relevant state tribunal, which can compel production of ledger records, bank statements and reconciliation documents as evidence.
This is exactly why the daily and monthly habits described earlier matter beyond audit season. A well-documented, consistently reconciled trust account gives an agency a clear, defensible record the moment a dispute arises, rather than a scramble to reconstruct what happened months after the fact. Agencies that keep signed reconciliations and ledger exports on hand resolve disputes faster and with far less back-and-forth than those piecing together records after a complaint lands.
Outsourcing trust accounting: what a specialist partner actually does
Specialist outsourced providers reduce an agency’s compliance risk by embedding daily receipting, reconciliations and owner disbursements into a disciplined routine, rather than leaving them to whoever has time between property inspections. Reliance Property Accounts specialises in tailored trust account management for Australian real estate agencies, adapting to each agency’s existing systems rather than forcing a new workflow onto the team.
What typically shifts to a specialist partner is the daily mechanical work: reconciliations, receipting, bill entry and disbursements. What stays with the agency is everything client-facing, approvals, relationships and final sign-off decisions. That division keeps the agency in control while removing the daily burden that causes most compliance failures.
— Kasie
Get trust accounts handled by Reliance Property Accounts
Outsourced trust accounting through Reliance Property Accounts covers the daily grind that compliance depends on: reconciliations, receipting, bill entry, owner disbursements and audit-ready documentation, built around the systems an agency already uses rather than a rigid template.
- Daily reconciliations and receipting handled by a dedicated trust accounting specialist.
- Audit-ready records compiled and maintained continuously, not assembled under deadline pressure.
- Agencies retain every approval and client-facing decision throughout.
Reach out through our about page to talk through what a tailored arrangement would look like for an agency’s own systems.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What is the 30% rent rule in Australia?
The 30% rule is an affordability benchmark, not an Australian law or a figure set by any regulator, originating in US public housing research and used to flag rental stress. Rent that the average Australian rental household already spends around 33.4% of income on rent, above the benchmark itself.
Who can audit trust accounts in NSW?
Trust account audits in NSW must be performed by an auditor qualified under section 115 of the relevant legislation, and the report must be lodged through the Auditor’s Report Online system. The Licensee in Charge remains responsible for ensuring the audit happens and is lodged on time.
What is trust accounting and how does it work?
Trust accounting is the practice of holding client money, rent, bonds and other funds, separately from an agency’s own money, recorded in a dedicated bank account registered with a Unique Identifying Number. Every transaction is tracked on a rental ledger and reconciled monthly against the bank balance to confirm nothing has gone missing or been misallocated.
Where can I get a rental ledger from?
A rental ledger is produced and held by the managing agent or landlord, and tenants in NSW can request a written rent statement, which the agent must provide within seven days. Many agencies now also make ledgers available continuously through a tenant portal rather than only on request.