A robust end of month process delivers accurate financial statements on deadline, and the single highest-impact habit is finishing complete reconciliations early, followed by a short, accountable sign-off. Everything else, including automation and task sequencing, exists to protect that outcome. This guide sets out the checklist, the controls and the governance steps that make it repeatable.
TL;DR:
How healthy is your trust account?
Book a complimentary 30-minute Trust Account Health Check and see where your processes could be improved.
Book a Free Health Check →
- Daily or weekly bank and trust reconciliations are essential, with a full month-end reconciliation required regardless of frequency, to ensure accuracy.
- Assigning clear ownership and deadlines for each task, such as cut-offs and journal postings, prevents delays and last-minute rushes during the close.
- Automating repetitive tasks like bank feed imports and recurring journal entries increases efficiency but requires human oversight for exceptions to maintain control.
- Regular reconciliation of all balance sheet accounts to independent sources, with proper segregation of duties, strengthens internal controls and deters fraud.
- Early handling of data cut-offs and proper triaging of reconciling items are crucial to avoiding delays caused by late source data or complex reconciliation issues.
Table of Contents
- Building a practical month-end checklist with clear task owners
- Reconciliations and internal controls that stand up to scrutiny
- Month-end certification: who signs what and why it matters
- Where to automate the close without losing control
- Common bottlenecks that slow the close and how to fix them
- What CPA Australia, IFRS and the ATO expect from your close
- Embedding repeatable month-end discipline
- How Reliance Property Accounts supports trust-account month-end work
- Sources
- FAQ
Building a practical month-end checklist with clear task owners
A close only runs on time when every task has a named owner and a date. Start by building a close calendar that lists each activity against the business day it falls on, whether that is day one or day five, and who signs it off.
- Lock the close calendar: assign each task to one person, with a backup, so nothing stalls waiting on a single staff member.
- Handle cut-offs early: confirm which invoices, receipts and payments belong in the current period before any ledger is touched.
- Post accruals and deferrals: capture revenue earned but not yet billed and expenses incurred but not yet invoiced, so the period reflects real activity rather than just cash movement.
- Prepare data readiness checks: confirm bank feeds, point-of-sale exports and subsidiary systems have all loaded before reconciliation begins.
- Post journals and adjustments: depreciation, prepayments, provisions and any correcting entries identified during review.
- Complete reconciliations and supporting schedules: every balance sheet account should tie to an independent source, not just the general ledger.
- Produce reports for reviewers: a profit and loss, balance sheet and cash flow summary, plus any variance commentary reviewers need to approve the close.
Tasks that commonly get rushed, and should not be, include:
- Reviewing suspense and clearing accounts for unresolved items.
- Confirming intercompany balances agree on both sides.
- Checking that payroll liabilities match the actual pay run.
Sequencing matters as much as the tasks themselves. Pre-close data readiness should be finished before reconciliations start, otherwise teams reconcile against incomplete figures and redo the work once late data arrives.
Reconciliations and internal controls that stand up to scrutiny
Bank accounts and trust accounts should be reconciled daily or at minimum weekly, with a full reconciliation at month-end regardless of frequency during the period. Sub-ledgers, including accounts receivable and accounts payable, need at least a monthly tie-out against the general ledger, with larger or higher-risk accounts sampled more closely.
- Reconcile every balance sheet account to an independent source, not just to last month’s closing figure.
- Separate who prepares a reconciliation from who reviews and approves it, or add a compensating independent review where teams are too small to split duties.
- Keep evidence that meets the ATO’s digital record-keeping rules, since clear digital reproductions of source documents are acceptable without retaining paper.
- Document the reconciling items that remain open, their age and who owns resolving them.
Regular reconciliations, properly performed and reviewed, are among the most effective controls a finance team can run. CPA Australia’s guidance on internal controls notes that reconciliations paired with segregation of duties make accurate reporting more likely and make concealing fraud far harder, even in small teams without formal structures.
Adequate documentation means a reviewer with no prior context could follow the reconciliation and understand what was checked, what didn’t match, and why it was accepted.
Month-end certification: who signs what and why it matters
Certification is the formal confirmation that the key close tasks, reconciliations, journals and control checks are genuinely complete, not just ticked off. It gives management something concrete to rely on when they sign off the broader financial statements.
Could outsourcing save your agency time and money?
Book a complimentary 30-minute Trust Account Health Check and see where your processes could be improved.
Book a Free Health Check →A minimal certification package should include:
- A list of reconciliations completed, with preparer and reviewer names.
- Confirmation that all planned journal entries, including accruals, have been posted.
- Sign-off from the preparer, a reviewer and, for material items, a controller or finance manager.
- A record of any exceptions, their resolution, or why they were accepted unresolved.
Certification should happen on a fixed date each cycle, with records retained in the same place every month. That consistency is what makes a close package audit-ready rather than reconstructed after the fact.
Where to automate the close without losing control
The highest-payback automation targets are the most repetitive: bank feed imports, recurring journal entries, standard report generation and routine reconciliations between systems that already use compatible data formats. Automating these frees reviewers to spend time on judgement calls instead of data entry.
- Automate bank and trust account imports first, since these feed almost every other reconciliation.
- Automate recurring journals, such as monthly depreciation or standard accruals, once the amounts are stable enough to template.
- Keep a human review point at every exception, so unusual transactions route to a person rather than clearing automatically.
- Pilot one process, measure the time saved and error rate, then extend it to the next task once it is proven.
Automation should remove repetitive data movement, not the judgement that catches genuine errors. A system that clears every reconciling item automatically is a control gap waiting to surface.
Pro Tip: Start automation with the task that causes the most rework each month, not the one that looks easiest to automate.
Common bottlenecks that slow the close and how to fix them
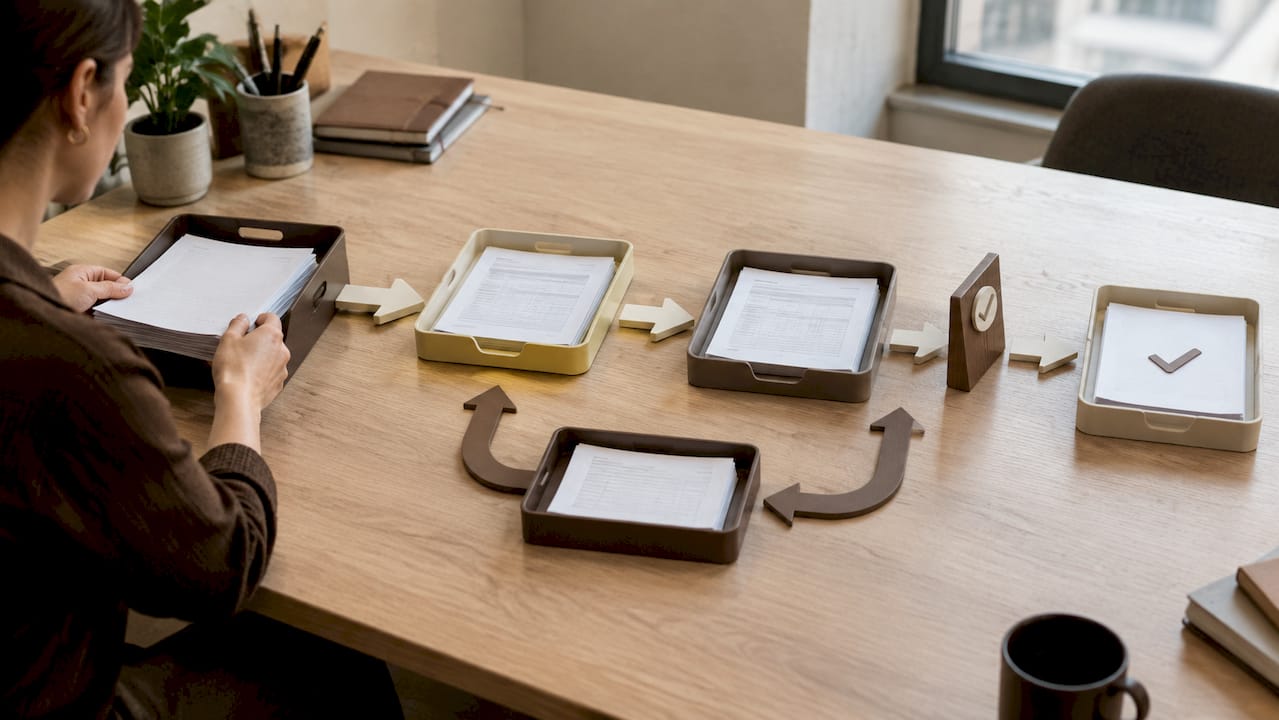
Late source data is the most common delay, usually traced to a single upstream system or person. Agree firm cut-off times with anyone supplying data and escalate early when a deadline slips.
- Triage reconciling items by size: clear small, obvious ones immediately, investigate medium items, and escalate large or unusual ones with a documented owner.
- Cross-train at least one backup person on every critical task to avoid delays when one staff member is unavailable.
- Standardise the chart of accounts and mapping rules across systems to cut the manual recoding that causes rework every cycle.
Fixing the upstream cause of a bottleneck is almost always faster than adding more review steps downstream.
What CPA Australia, IFRS and the ATO expect from your close
IAS 1 requires financial statements on an accrual basis with set presentation and comparative information requirements, shaping how month-end judgement calls get recorded.
Regular reconciliations and segregation of duties are core controls that support accurate reporting and deter concealment of fraud.
That principle, drawn from CPA Australia’s internal controls guidance, sits alongside the ATO’s digital record-keeping rules as the backbone of a defensible close.
Embedding repeatable month-end discipline
The processes that hold up under pressure are the ones built around how a team already works, not the ones that force a new system on top of existing habits. Adapting to a business’s existing tools reduces disruption and gets a reliable close running sooner.
— Kasie
How Reliance Property Accounts supports trust-account month-end work
Real estate agencies carry an extra layer of month-end complexity: trust account reconciliations, owner disbursements and compliance obligations sit on top of standard bookkeeping. Specialized providers often handle this daily rather than leaving it to pile up at month-end.
- Daily reconciliations and receipting help keep trust ledgers current rather than reconstructed at close.
- Owner disbursements and supplier payment processing handled as part of the regular cycle.
- Internal ledger review and compliance support aimed at keeping accounts audit-ready year-round.
Outsourcing suits agencies that want their internal team focused on property management rather than daily trust reconciliations. Such services often adapt to each agency’s existing systems rather than imposing a new workflow. Visit the outsourced trust accounting page to start a conversation about your agency’s trust account close.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- ATO — digital record keeping for business
- CPA Australia — internal controls for small business
- IFRS — IAS 1 presentation of financial statements
FAQ
What is the process of month-end closing?
Month-end closing is the set of tasks finance teams complete at the end of each period to confirm the books are accurate, including cut-offs, journals, reconciliations and reviewer sign-off. The goal is a finalised, accurate set of financial statements ready for management or reporting use.
What are the steps for the month-end closing?
The core steps are handling cut-offs, posting accruals and journals, completing reconciliations against independent sources, preparing reports, and certifying that everything is complete. Each step should have a named owner and a fixed date on the close calendar.
What are the 5 stages of the accounting process?
Definitions vary, but a common version covers transaction recording, journal entries, posting to the ledger, preparing a trial balance, and producing final financial statements. Month-end closing activities sit across the later stages, particularly adjusting entries and statement preparation.
What do accountants do at the end of the month?
Accountants reconcile bank, trust and sub-ledger accounts against independent sources, post accruals and adjusting journals, and prepare reports for review. They also resolve outstanding reconciling items and complete sign-off documentation to support the close.
How can a business shorten its month-end close cycle?
Shortening the close usually comes from fixing late source data at its origin, triaging reconciling items by size, cross-training staff on critical tasks, and automating repetitive work such as bank imports and recurring journals. Keeping human review on exceptions, rather than removing it entirely, protects accuracy while speeding up the routine work.